Tourism Workforce Contracts as Summer Season Ends
The tourism sector[1] in September 2026 saw a sharp seasonal contraction of the workforce from August[2], as students returned to school and summer operations wound down. Tourism employment fell by 7%, a steeper drop than the same time last year (around 5%), and tourism accounted for about 87% of the roughly 187,000 jobs lost across the national economy.
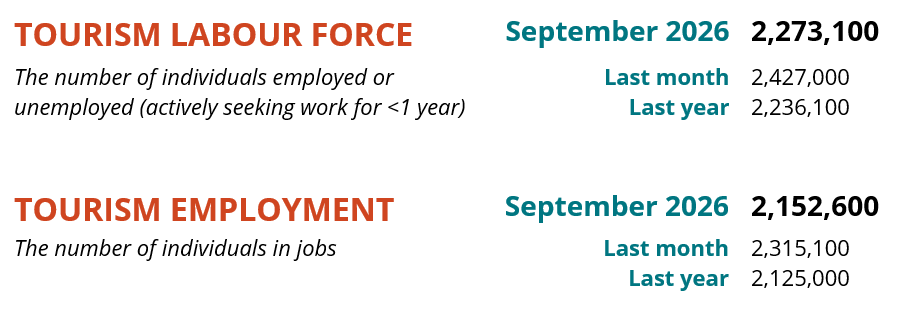
Table 1 provides a snapshot of each industry group’s performance across labour force, employment, and unemployment, as compared with August 2026 [MoM] and September 2025 [YoY], and with September 2019 as a pre-pandemic baseline. Small arrows represent changes of less than 1% (or one percentage point, in the case of unemployment).

At the industry group level, the month-over-month picture was largely one of seasonal contraction, with large losses in labour force and employment in recreation and entertainment and accommodations, and smaller losses in food and beverage services. Transportation was the exception, with gains in both labour force and employment and a large drop in unemployment.
Compared with last year and with 2019, the sector as a whole remained larger, driven by food and beverage services and recreation and entertainment, while accommodations and travel services remained below both benchmarks. Unemployment rates were higher than last year in most industry groups.
Tourism Sector
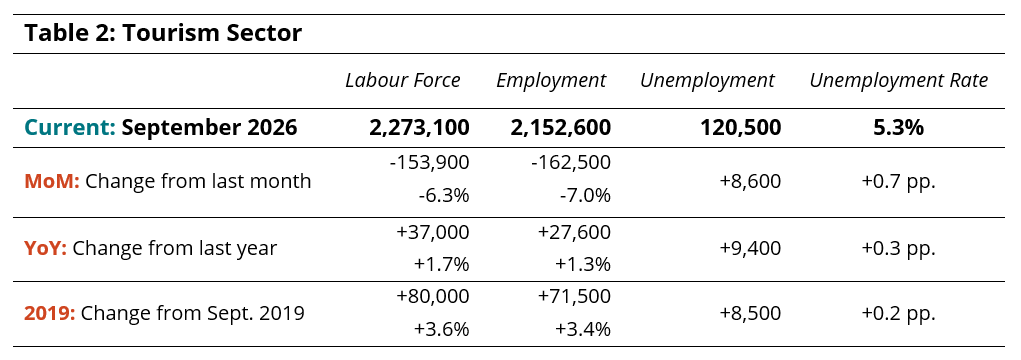
At the aggregate sector level (Table 2), employment fell by 7.0% from August, a loss of around 163,000 workers. The labour force shrank slightly less (-6.3%), which pushed the unemployment rate up by 0.7 percentage points, to 5.3%. In spite of the seasonal drop, the sector was still larger than this time last year (employment +1.3%) and remained around 3.4% bigger than in 2019.
As a point of comparison, the wider national economy also contracted, with the labour force shrinking by around 472,000 people and employment falling by around 187,000 (-0.9%). Because the labour force fell faster than employment, the economy-wide unemployment rate dropped from 7.3% in August to 6.2%. Tourism accounted for around 87% of the net employment losses across the entire economy in September.
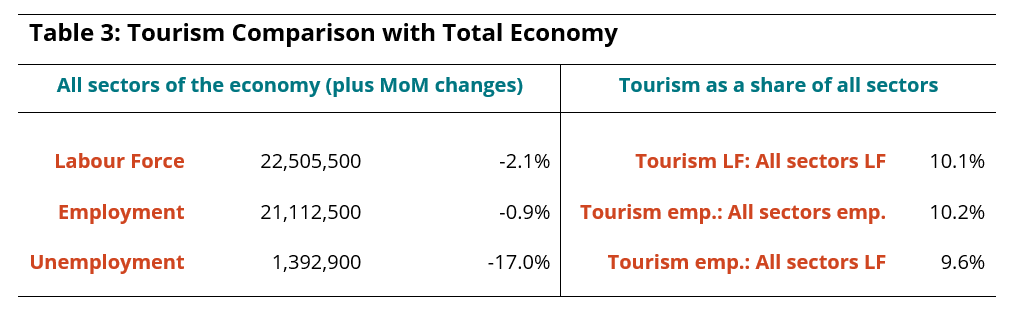
In September, tourism’s share of all employment in Canada fell to 10.2%, down 0.7 percentage points from its summer peak in August, but slightly higher than in September 2025 (10.1%). The share was below its pre-pandemic level (10.8% in September 2019), reflecting both the seasonal nature of tourism employment and the growth of the wider economy since 2019 (total employment +9.7%).
Part-Time and Full-Time Employment
Changes in the ratio of part-time to full-time employment provide a useful perspective on the stability of the tourism workforce. At the aggregate level, there was a pronounced shift towards part-time employment from August (Figure 1), with the part-time share of tourism employment rising from 32.4% to 38.2%. Full-time employment fell by around 236,000, while part-time employment grew by around 73,000, consistent with seasonal full-time summer positions ending and students returning to school.
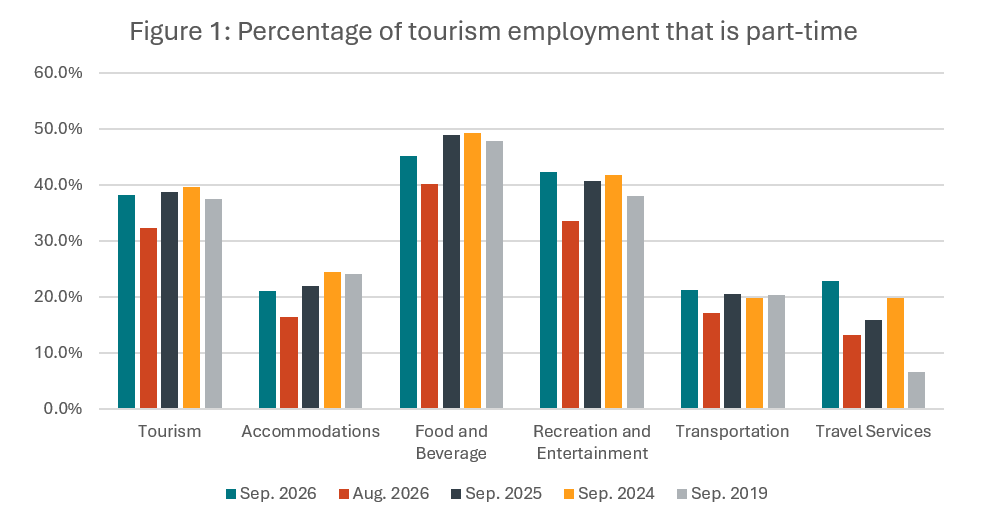
Relative to last year, the overall part-time share was little changed (38.7% in September 2025) and remained close to 2019 levels (37.5%). Food and beverage services continued its shift towards full-time employment, with the part-time share falling 3.8 percentage points from last year to 45.2%, which was also below 2019 levels. Recreation and entertainment, by contrast, leaned further towards part-time work than in either 2025 or 2019. Accommodations and transportation showed little change from last year, and the large shift in travel services was likely due to data inconsistencies.
Hours Worked
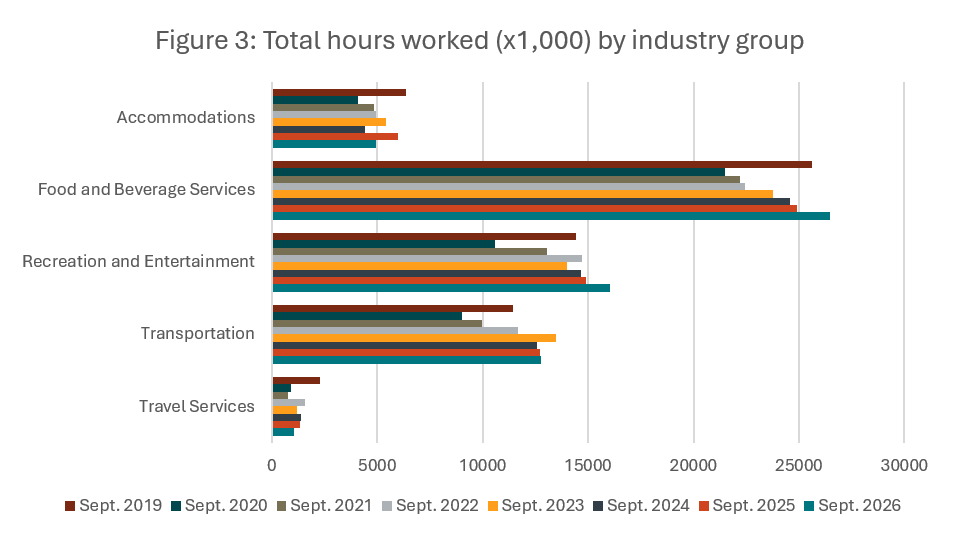
The total number of hours worked provides another useful insight into the stability of the tourism workforce (Figure 2), particularly where part-time employment accounts for a substantial proportion of the workforce, and where businesses can respond to changes in demand by scaling hours worked more quickly than they can adjust their baseline staff rosters (raw employment numbers).
September 2026 saw a seasonal drop in hours worked relative to August (-8.1%), steeper than the equivalent drop last year (-4.9%). Nevertheless, hours worked remained 2.4% higher than in September 2025, and 1.9% above 2019 levels.

At the industry group level (Figure 3), year-over-year gains were again concentrated in food and beverage services (+6.2%) and recreation and entertainment (+7.8%), the two biggest overall employers in tourism, while transportation was roughly flat (+0.6%). Accommodations (-17.5%) and travel services (-21.3%) saw substantial losses from last year. Transportation, recreation and entertainment, and food and beverage services all surpassed 2019 levels, while hours worked in accommodations remained around 23% lower than before the pandemic, and travel services was less than half of its 2019 level.
Youth in Tourism
Tourism plays an important role in attaching young people to employment, with its seasonality that aligns closely with academic calendars and its range of flexible opportunities for part-time work throughout the year. The skills and experiences that young Canadians gain through working in tourism will serve them well throughout their lives, regardless of which sector they end up working in. At a time when public discourse is heavily focused on youth unemployment and the myriad challenges facing youth, tourism is well positioned to support youth onto the first rung of the employment ladder.
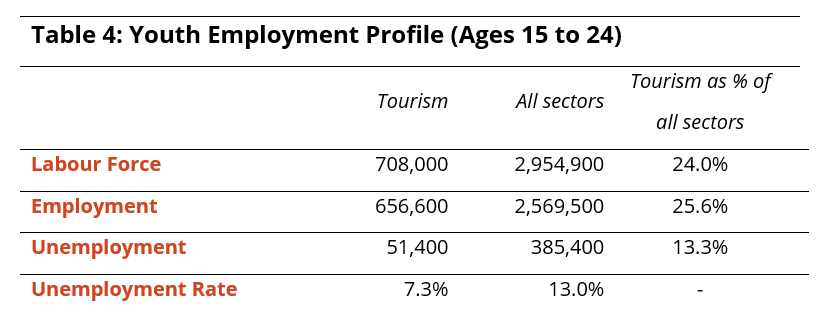
The unemployment rate in September for youth in tourism was just over half of what it was across the total economy (Table 4), at 7.3% compared with 13.0%. However, the tourism youth unemployment rate rose by 2.8 percentage points from August, while its economy-wide counterpart eased by 0.5 percentage points.
Youth employment in tourism fell by around 186,000 from August as students returned to school, which is more than the sector’s total net employment loss (around 163,000), meaning that employment among tourism workers aged 25 and older actually grew slightly. Even so, around one in four working youth (25.6%) held jobs in tourism.
Industry Closeup: Accommodations
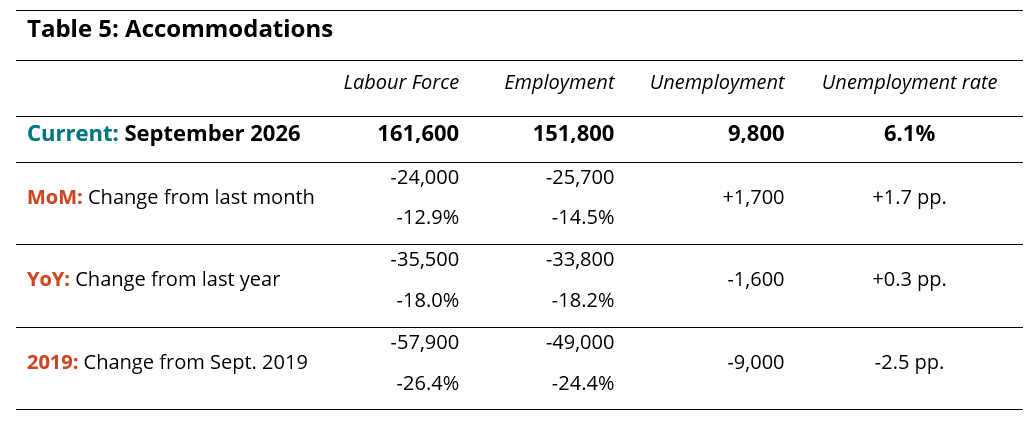
The accommodations industry continued to lose ground in September (Table 5). Around 26,000 people left work in the industry from August (-14.5%), bringing total employment to just under 152,000, and pushing the unemployment rate up by 1.7 percentage points, to 6.1%. The industry was significantly smaller than this time last year (-18.2%), and remained around one-quarter smaller than before the pandemic (-24.4%). Hours worked tell a similar story, down 17.5% from last year.
Industry Closeup: Food and Beverage Services
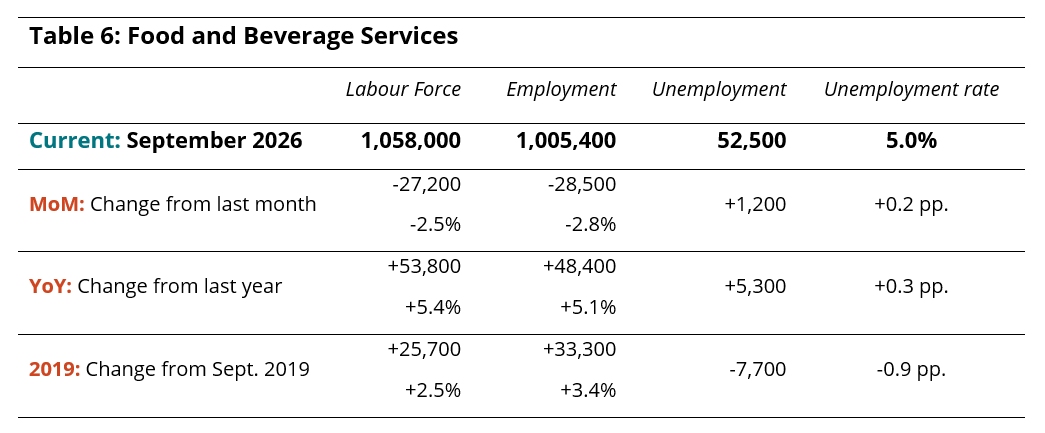
Food and beverage services saw modest losses from August (Table 6), with employment down 2.8%, but still sitting just above one million—a much smaller decline than the other large industry groups. Unemployment was nudged up slightly to 5.0%. Year-over-year growth remained solid at above 5%, and employment was over 3% higher than before the pandemic. The industry also continued its shift towards full-time work, with full-time employment up nearly 13% from last year.
Industry Closeup: Recreation and Entertainment
Recreation and entertainment accounted for the bulk of the sector’s monthly losses (Table 7), with employment falling by around 121,000 (-17.0%), likely reflecting the end of the summer season for many seasonal attractions and events. Almost all these losses were in full-time work (around -131,000), while part-time employment grew slightly. The unemployment rate rose by 2.9 percentage points to 7.3%, the highest among the tourism industry groups. Even so, employment remained around 32,000 higher than last year and around 84,000 higher than before the pandemic, although unemployment was also higher than in both 2025 and 2019.

Industry Closeup: Transportation
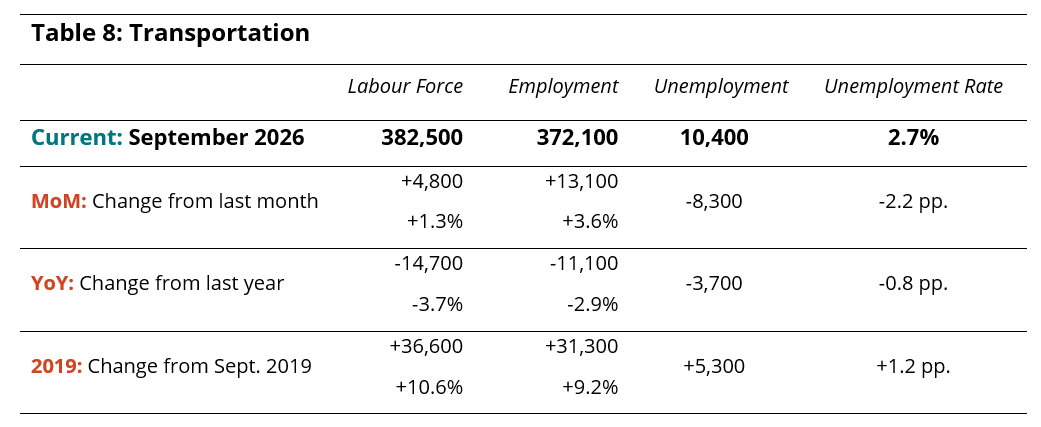
Transportation was the only tourism industry group to grow from August (Table 8), adding around 13,000 workers (+3.6%) and bringing the unemployment rate down by 2.2 percentage points to 2.7%, the lowest in the sector. Employment was slightly lower than this time last year (-2.9%), but remained over 9% higher than before the pandemic. As noted previously, it is difficult to determine what is driving this increase at this level of granularity, although it seems likely that it is at least partially due to an increase in ride-share drivers.
Industry Closeup: Travel Services
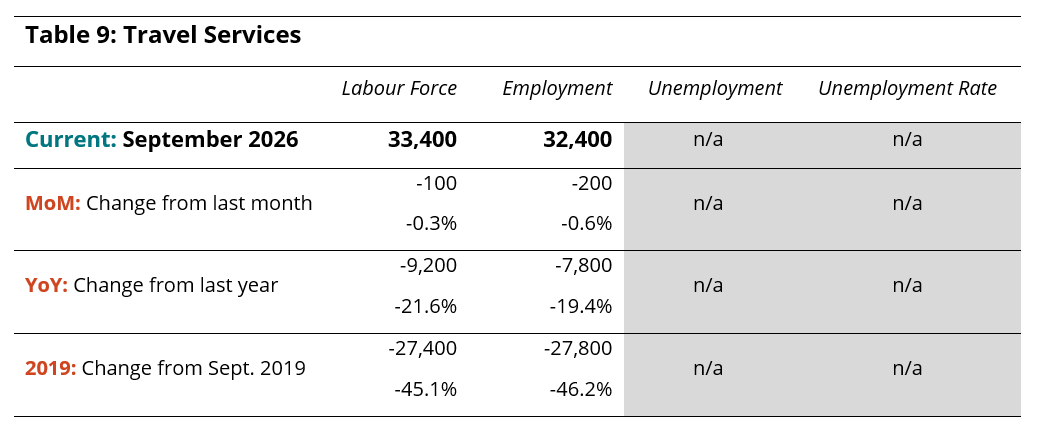
As noted previously, the travel services industry is not always reliably represented in the Labour Force Survey data, due to the sampling methods of the survey and the small size of this industry group. This means that employment and labour estimates are prone to disproportionately large swings from month to month, and that small changes in absolute terms can become exaggerated when normalized to percentages. Table 9 provides LFS estimates for travel services in September 2026, but should be used cautiously. Estimates were little changed from August, but remained around one-fifth lower than last year and roughly half of their 2019 level.
Provincial Perspectives
The Canadian economy is subject to some pronounced regional differences, and that is particularly true in the tourism sector. Figure 4 provides a comparison of provincial unemployment rates, for the tourism sector in particular and for the total labour force (i.e., comprising all industries).
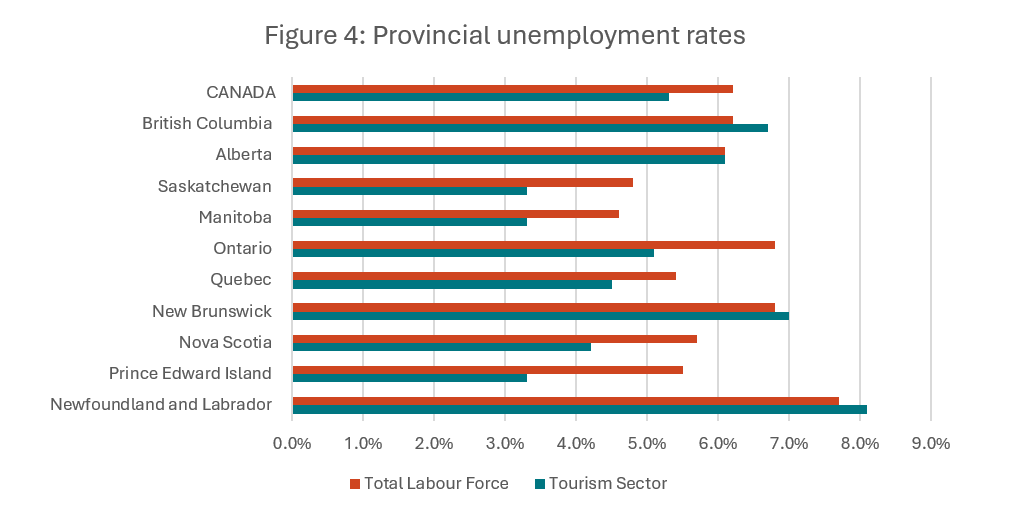
In September, the national tourism unemployment rate was 5.3%, below the economy-wide national average of 6.2%. However, unlike in August, when tourism unemployment rates were lower than economy-wide rates in every province, tourism rates were higher than those across the broader economies of Newfoundland and Labrador, New Brunswick, and British Columbia, and on par in Alberta. Tourism unemployment rates ranged from 3.3% in Prince Edward Island, Manitoba, and Saskatchewan, to 6.7% in British Columbia and 8.1% in Newfoundland and Labrador.
Provincial Summaries for September 2026
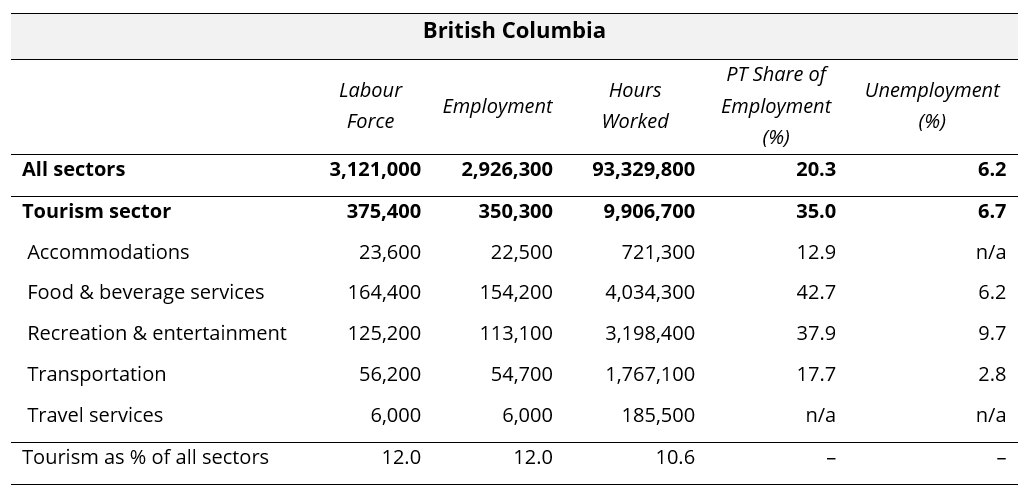
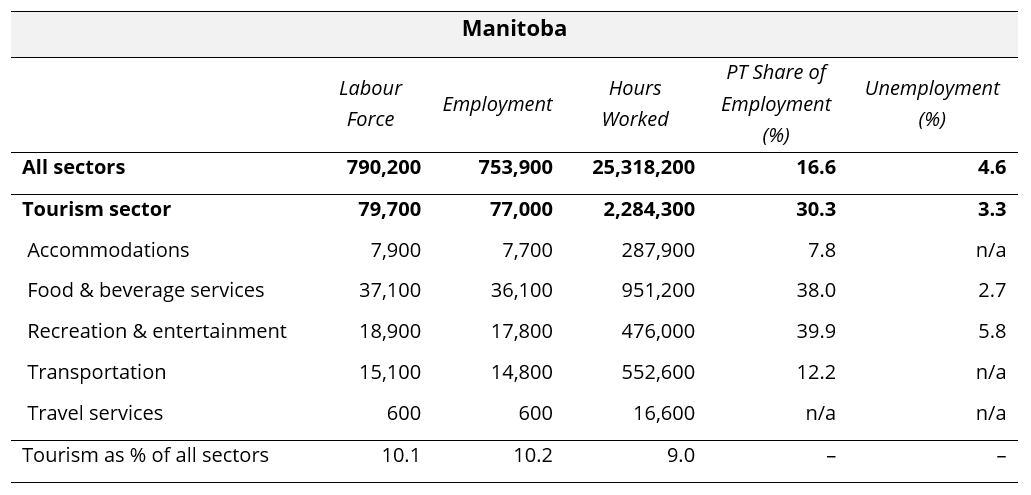
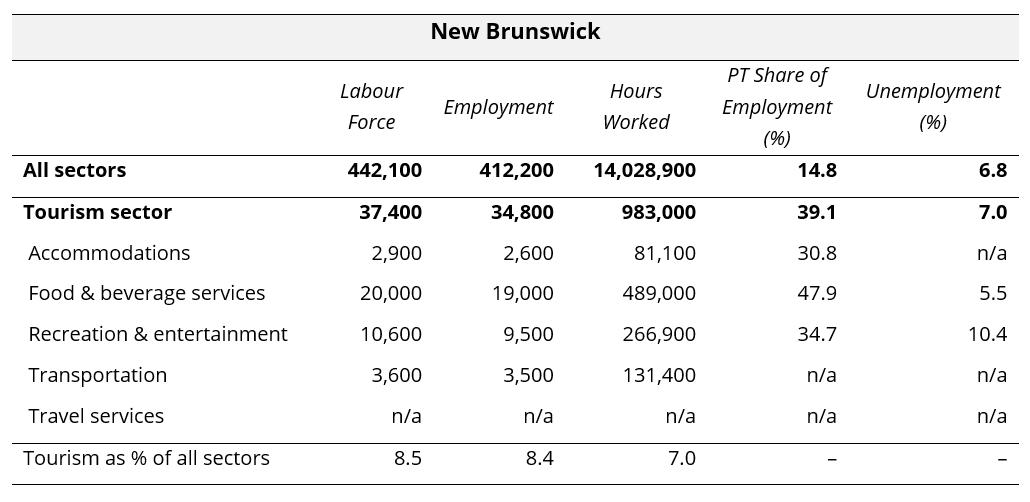
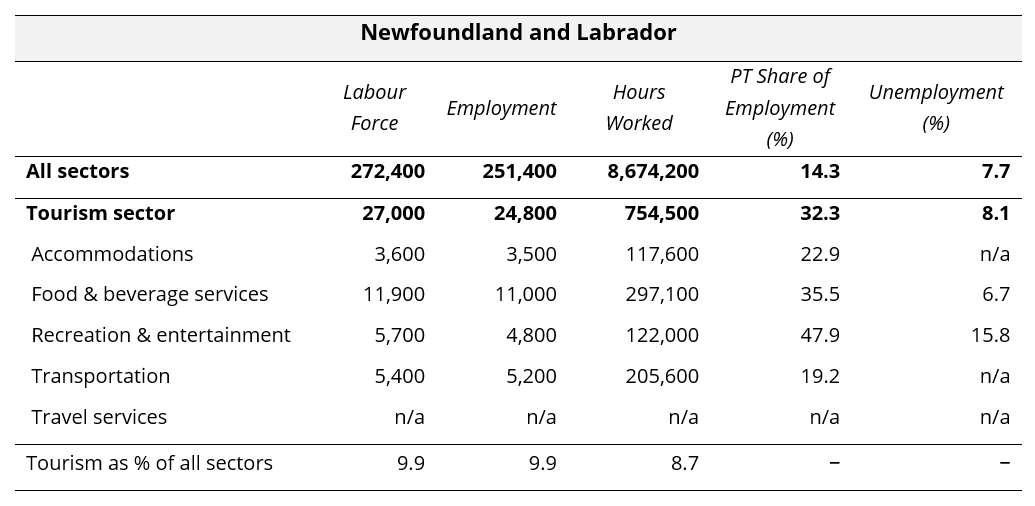
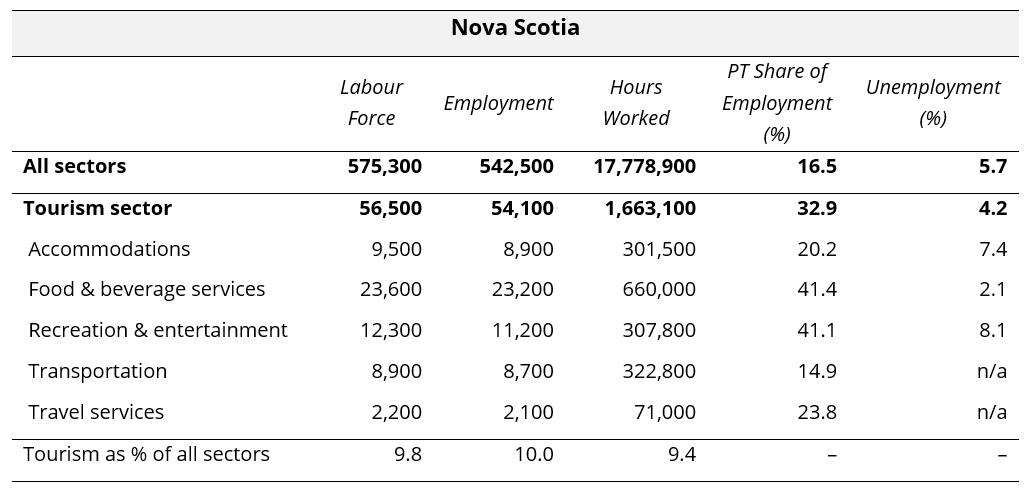
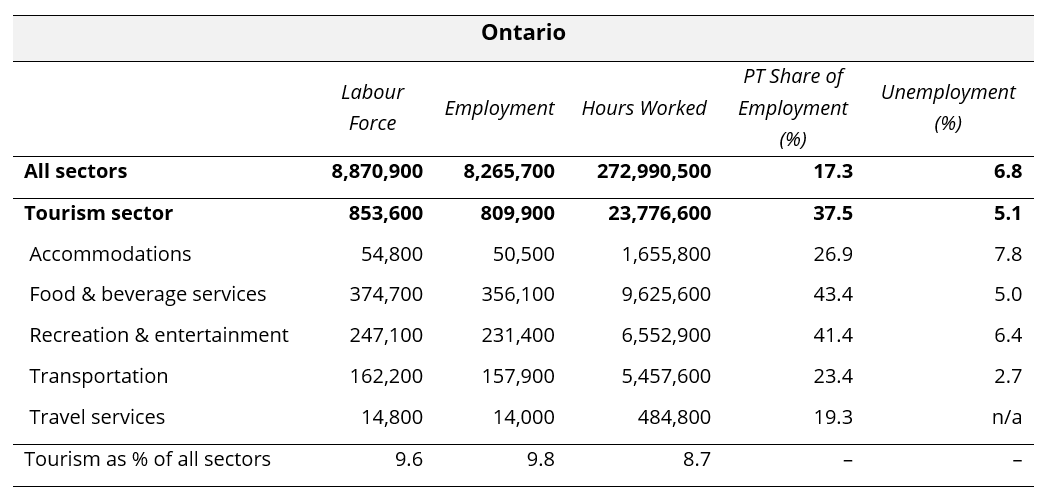
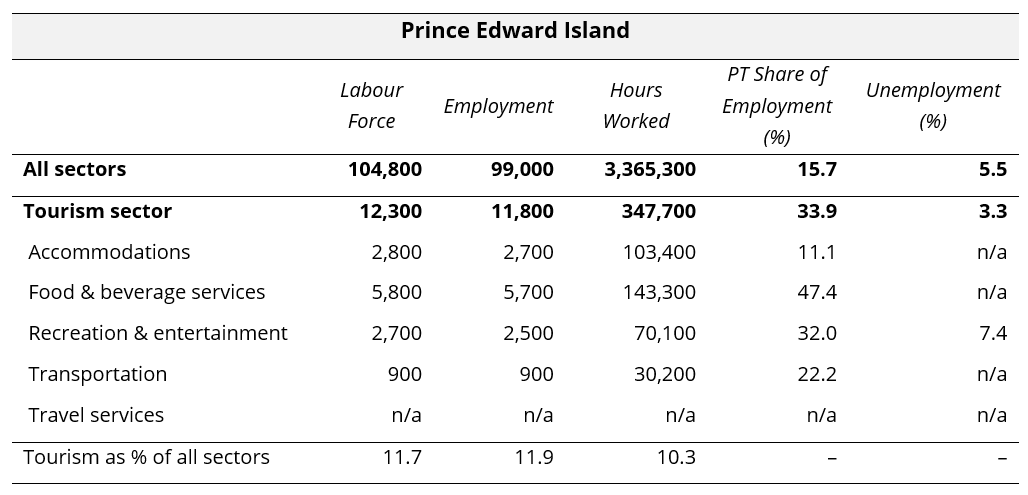
The following ten tables provide September 2026 summaries for the provinces, focusing on tourism and its five industry groups. Comparison data is provided for the larger provincial economy, as a benchmarking reference. Seasonally unadjusted estimates are provided for labour force, employment, and hours worked, and the final row of each table indicates tourism’s share of each of these metrics. The share of work that is part-time (as opposed to full-time) is also provided, as a rough indicator of the labour composition, as well as the unemployment rates.
Where data was not available due to suppression from Statistics Canada, “n/a” has been entered in the table. The three territories are not included in the LFS releases at this level of granularity, so no comparison is possible between the territories and the provinces. The provinces are listed alphabetically.



View more employment charts and analysis on our Tourism Employment Tracker.
[1] As defined by the Canadian Tourism Satellite Account. The NAICS industries included in the tourism sector those that would cease to exist or would operate at a significantly reduced level of activity as a direct result of an absence of tourism.
[2] SOURCE: Statistics Canada Labour Force Survey, customized tabulations. Based on seasonally unadjusted data collected for the period of September 13 to 19, 2026.